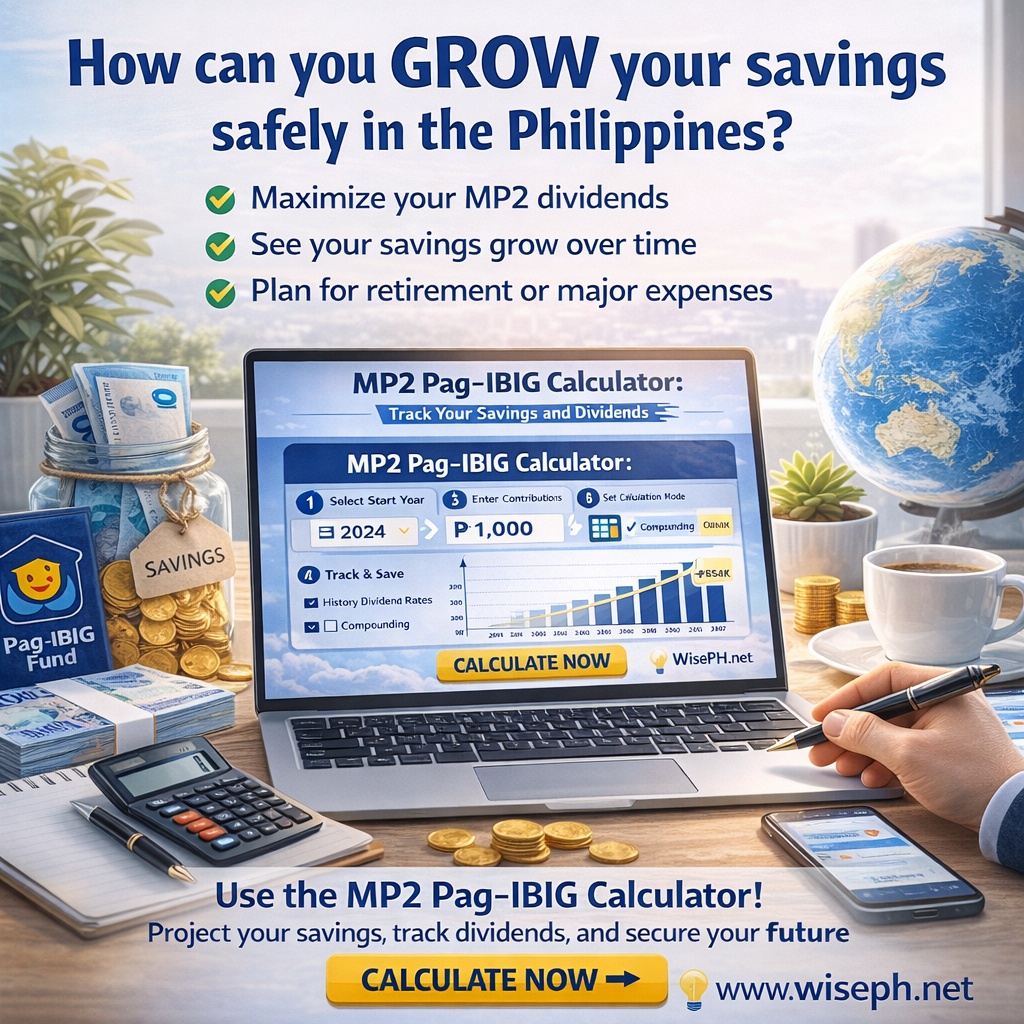
The most common question people ask me about MP2 is: how much will I actually earn? The MP2 calculator below answers that exactly, year by year, peso by peso. No spreadsheet needed.
I compared stocks, time deposits, bonds, and crypto before I chose MP2. Stocks were too volatile. Time deposits were too safe in the wrong way; the returns barely moved. Crypto was a gamble I wasn’t ready for.
In fact, MP2 was different: government-backed, tax-free dividends, and consistent returns that beat every bank product I compared. I deposited ₱50,000 in October 2017 and left it alone. At maturity in 2021, I walked away with ₱66,092.38. Use the MP2 calculator below before you decide on any amount.
MP2 savings calculator
The MP2 calculator estimates your total payout at maturity based on three inputs: how much you deposit, how often you deposit, and whether you want dividends paid out yearly or reinvested. Enter your numbers, pick your settings, and the tool gives you a full 5-year projection.
MP2 Pag-IBIG Calculator
Dividend Rates (Historical, Current, Future)
| Year | Dividend Rate (%) | Action |
|---|
Calculation Mode
Deposits
| Year | Month | Contribution (₱) |
|---|
Total Contribution
Total Dividend
Final Value
Notes: deposits within a year earn weighted dividends. In compound mode, dividends are added to the balance and earn full-year dividends in subsequent years. You can add previous, current, or future years. Future years start with 0% by default.
Here is what each field means:
- Monthly contribution: how much you deposit each month. Minimum is ₱500.
- Lump sum or one-time deposit: for a single large contribution or irregular deposits
- Dividend option: annual payout sends dividends to your account each year; compounding reinvests them for higher total returns
- Dividend rate: use the current declared rate or the historical average for long-term projections
If you have not enrolled in MP2 yet, read the guide on how to open an MP2 account before running the calculator. For existing members, check your current MP2 balance online first so your numbers are accurate.
Annual payout vs. dividend compounding: which should you pick?
Dividend compounding reinvests your earnings back into your balance. As a result, your next cycle earns dividends on a larger amount. Annual payout sends dividends to your account each year, which is useful if you need the cash flow now.
| Option | Best for | Outcome |
|---|---|---|
| Annual payout | Need yearly income | Lower total at maturity |
| Compounding | Maximum growth | Higher total at maturity |
I chose compounding without hesitation. When dividends compound, your money earns on itself year after year. Generally, the longer you hold, the bigger the gap between the two options.
Granted, the only downside is the 5-year lock-in. You will not touch that money until maturity. If you need liquidity, annual payout makes more sense. If you can leave it alone, compounding wins every time. For a side-by-side peso comparison, see the full breakdown of lump sum vs. monthly contributions in MP2 to see how deposit frequency also affects your final number.
What is MP2 and why does it beat most savings options?
MP2 (Modified Pag-IBIG II) is a voluntary savings program from Pag-IBIG Fund. Specifically, it pays annual dividends, protects your principal with full government backing, and charges zero tax on your earnings.
| Savings option | Average return | Tax on earnings | Risk |
|---|---|---|---|
| Regular savings account | 0.1–0.5% | 20% final tax | None |
| Time deposit | 1–3% | 20% final tax | None |
| MP2 savings | 5–8% | None | None |
| Stocks | Varies | Capital gains | High |
After comparing all of them, I kept coming back to one fact: MP2 dividends are completely tax-free. Everything you earn is yours. Compare that to a time deposit where 20% of your return goes straight to withholding tax. The gap adds up fast over five years.
MP2 also earns more than the regular Pag-IBIG savings program (Program 1). If you want a clear breakdown of how the two differ, read the guide on how Pag-IBIG regular savings compares to MP2 before you decide which to prioritize.
MP2 dividend rate history: 2011 to 2025
Pag-IBIG declares the MP2 dividend rate annually based on fund performance. The rate is not fixed, but over 15 years it has consistently outperformed savings accounts and time deposits.
| Year | MP2 dividend rate |
|---|---|
| 2011 | 4.63% |
| 2012 | 4.67% |
| 2013 | 4.58% |
| 2014 | 4.69% |
| 2015 | 5.34% |
| 2016 | 7.43% |
| 2017 | 8.11% |
| 2018 | 7.41% |
| 2019 | 7.23% |
| 2020 | 6.12% |
| 2021 | 6.00% |
| 2022 | 7.03% |
| 2023 | 7.05% |
| 2024 | 7.10% |
| 2025 | 7.12% |
The 2021 dip to 6.00% happened during the pandemic. Banks were offering under 2% on time deposits at the same time, and that 2% was still taxed at 20%. A tax-free 6% during a global economic downturn was a strong result, not a disappointment. By 2022, the rate had already bounced back to 7.03%.
When people tell me they’re hesitant because the rate isn’t fixed, I tell them to run the MP2 calculator using the 5-year average rate and compare it against everything else available at the same time. The 5-year average tells a better story than any single year. For the full breakdown of the latest declared rate and how it’s calculated, read the guide on the MP2 dividend rate for 2025.
What your MP2 calculator results look like in real life
My account
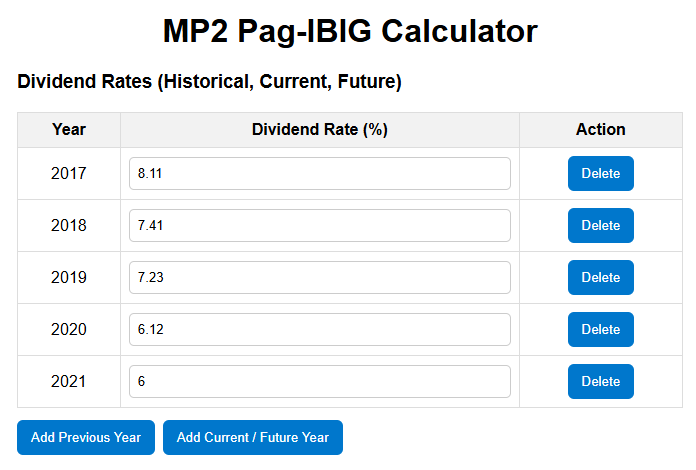
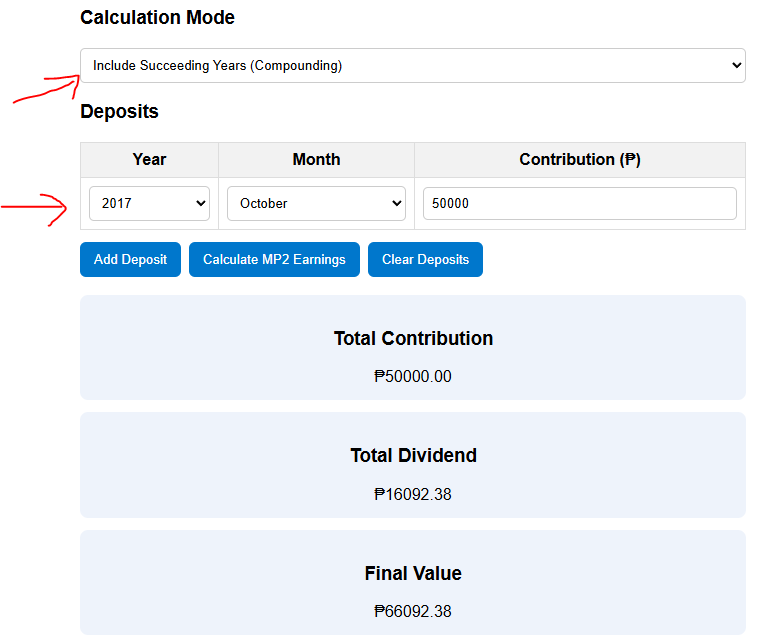
I deposited ₱50,000 in October 2017 and chose dividend compounding. No additional deposits; I left it alone for 5 years. At maturity in 2021, the total was ₱66,092.38. Overall, that’s ₱16,092.38 in tax-free earnings, no forms to file, no withholding to track.
An OFW friend’s account
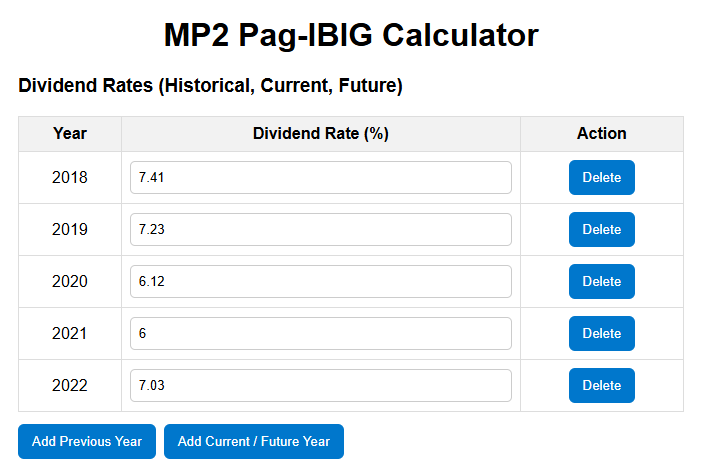
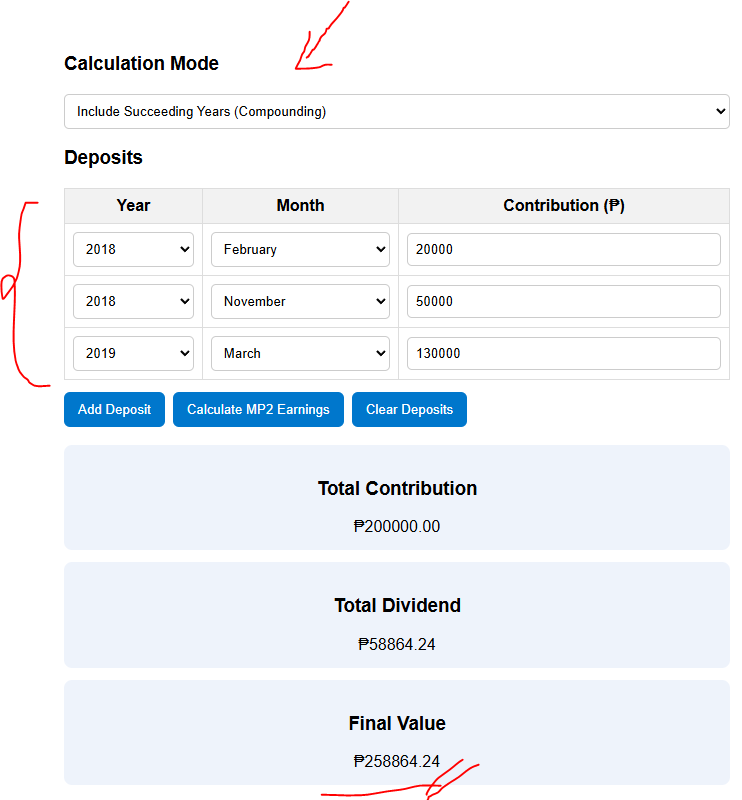
A friend working abroad made three deposits: ₱20,000 in February 2018, ₱50,000 in November 2018, and ₱130,000 in March 2019. Total invested: ₱200,000. Eventually, at maturity in 2022, the payout was ₱258,864.24, a gain of ₱58,864.24.
When he saw that number, he wanted to re-invest immediately. Once you see actual results from the MP2 calculator, the hesitation disappears. If you’re approaching maturity, read the full guide on what happens to your MP2 after 5 years, and the step-by-step guide on how to claim your MP2 savings so you’re ready when the date arrives.
The staggered account strategy for steady income
You can open more than one MP2 account. Believe it or not, most people don’t realize this. I started with one, then opened additional accounts about 6 to 12 months apart, depositing a lump sum into each. When you stagger the opening dates, each account matures at a different time. Instead of one big payout every 5 years, you get regular payouts on a rolling cycle.
Set it up early and the payouts become predictable. Ten minutes of planning, years of consistent returns. Read the full guide on opening multiple MP2 accounts to understand the limits and how each account is tracked separately in Virtual Pag-IBIG.
Is MP2 worth it if you only have ₱500 a month?
Yes. Start with ₱500. Plug it into the MP2 calculator and run a 5-year projection. The return on that amount is modest, but the real value is what you learn. You see exactly how the contribution schedule works, how dividends accumulate, and what the payout process looks like at maturity. Ultimately, that knowledge is what pushes you to scale up later.
Notably, MP2 dividends are completely exempt from income tax. Nothing to declare, nothing to withhold. Your full return stays in your pocket, and it won’t complicate your annual ITR filing either. The easiest way to keep contributions consistent is to pay monthly via GCash, Maya, or online banking so you never miss a cycle.
Browse all our Pag-IBIG guides for the full picture, from opening your first account to claiming your payout at maturity.
Frequently asked questions about the MP2 calculator
- What is the MP2 Pag-IBIG savings calculator?
- The MP2 calculator estimates your total return over 5 years based on your contribution amount, frequency, and dividend option. Use it to plan how much to invest before you commit.
- What is the minimum amount to invest in MP2?
- The minimum contribution is ₱500. There is no maximum. You can start small and add to your account anytime.
- Is the MP2 dividend rate fixed every year?
- No. Pag-IBIG declares the rate annually based on fund performance. Since 2011, it has ranged from 4.58% to 8.11%. The rate for 2025 is 7.12%.
- What is the difference between annual dividend payout and dividend compounding in MP2?
- Annual payout credits your dividends to your account each year. Compounding reinvests them so they earn more dividends in the next cycle. Compounding gives a higher total at maturity.
- Can I open multiple MP2 accounts?
- Yes. Opening accounts 6 to 12 months apart is a smart strategy. Each account matures separately, giving you a regular payout cycle instead of one lump sum every 5 years.

Comments 6